Business
What the insurance industry sees when it looks at your home
Find out what criteria the insurance industry uses when looking at your home. Learn insider tips and how to ensure your home is fully covered.

What the insurance industry sees when it looks at your home is why its replacement cost matters more than its market value, and that home upgrades can improve protection or increase coverage needs. Your property’s location also affects more than just your premium; insurers consider how well you maintain your home, too.
The Pew Research Center reports that 71% of American homeowners say their home insurance costs have gone up. Increasing costs can be a huge financial burden, so finding ways to reduce them can provide much-needed relief.
The insurance industry is huge, and they’ve got experience handling property insurance evaluation processes. As a homeowner, you may feel hopeless at times when fighting these giants.
What Does the Insurance Industry See When It Looks at Your Home?
When assessing home insurance, keep in mind that insurers want to protect their bottom line. These are the insurance coverage factors they weigh.
Why Your Home’s Replacement Cost Matters More Than Its Market Value
When homeowners get home insurance, they assume their policy should match what their house could sell for, but insurers evaluate something entirely different: replacement cost. This is the estimated cost to rebuild the home after a total loss, using today’s labor rates and material prices.
Construction costs can rise rapidly due to:
- Inflation
- Local labor shortages
- Changes in building codes
Insurers also consider the property’s size, layout, roofing materials, custom features, and overall complexity.
Home Upgrades Can Improve Protection or Increase Coverage Needs
Not every renovation affects insurance in the same way. Some upgrades reduce risk, but others increase the home’s rebuilding cost or create additional liabilities.
These installations may lower the chances of future claims:
- New electrical system
- Impact-resistant roof
- Modern plumbing
These can increase the amount of insurance needed:
- Luxury finishes
- Custom cabinetry
- Solar panels
- Detached workshop
Even seemingly minor projects can change your house’s insured value, so keep records of permits, contractor invoices, and before-and-after photos whenever you make home improvements. Sharing these documents with your insurer allows coverage limits to be updated before a loss happens.
Your Property’s Location Influences More Than Just Your Premium
Insurance companies examine more than just your house; they also assess where it’s located. These factors all influence how they evaluate a property:
- Local weather patterns
- Wildfire exposure
- Hail frequency
- Hurricane risk
- Crime statistics
- Proximity of fire departments
Homeowners obviously can’t change their location, but they can often reduce risk through proactive measures, such as:
- Trimming trees away from the house
- Installing storm shutters where appropriate
- Improving exterior lighting
- Reinforcing vulnerable entry points
You should also understand the environmental risks specific to your area. This can help you determine whether optional endorsements or separate policies are worthwhile.
Insurers Also Consider How Well You Maintain Your Home
Your home’s overall condition can influence both insurability and long-term coverage options. Insurers often look at the age and condition of major systems, such as:
- The roof
- HVAC equipment
- Plumbing
- Electrical components
Deferred maintenance can increase the risk of water intrusion and structural issues, and this is concerning for insurers. To mitigate this, have routine inspections, replace aging components before they fail, and keep maintenance records. It’s also wise to create a home inventory with photos or videos of valuable belongings and update it annually.
What Are Red Flags for Insurance Companies?
Insurance companies look for home risk factors that suggest a higher likelihood of future claims or increased repair costs. Common red flags include:
- A history of frequent insurance claims
- Lapses in coverage
- Unpermitted renovations
- Outdated building systems that have exceeded their expected service life
Visible structural issues, poor drainage, or safety hazards may also raise concerns during underwriting or policy renewal.
In addition, discrepancies between the information provided on an application and the property’s actual condition can lead to delays or additional review. You can avoid this by keeping accurate records of repairs, obtaining permits for major projects, addressing maintenance issues promptly, and notifying your insurer when you complete significant improvements.
Frequently Asked Questions
What Are the 5 Cs of Insurance?
The five Cs of insurance explain the key principles that help homeowners choose and maintain the right coverage. Organizations define them slightly differently, but they are generally:
- Coverage: Types of losses your policy protects against, such as fire, wind, or theft
- Cost: Includes premiums, deductibles, and any discounts you may qualify for
- Claims: Measures how efficiently an insurer handles damage reports and payouts
- Customer service: Reflects the company’s responsiveness and support throughout the policy period
- Credibility: Considers the insurer’s financial strength, licensing, and reputation for paying valid claims
Evaluating all five factors provides a more complete picture than simply choosing the lowest premium.
What Not To Tell Your Insurance Company?
When you’re filing a homeowners insurance claim, it’s important to provide truthful and accurate information without making assumptions or speculative statements. You should avoid guessing about the cause of damage if it hasn’t yet been determined, as investigations may reveal different findings.
Don’t exaggerate repair costs or claim damaged property that wasn’t actually affected, either. Inaccurate information can delay processing or even result in claim denial.
You should instead document the damage with photos and save receipts for emergency repairs. You should also answer questions based on facts you know firsthand.
What Is the Most Common Damage to Your Home That Insurance Does Not Cover?
One of the most common forms of home damage not covered by standard homeowners insurance is flood damage resulting from rising water outside the home. These things typically require a separate flood insurance policy:
- Heavy rainfall
- Overflowing rivers
- Storm surge
- Flash flooding
Other frequently excluded things are damage caused by:
- Gradual wear and tear
- Deferred maintenance
- Mold resulting from long-term leaks
- Pest infestations
- Foundation settling due to normal aging
This Is What the Insurance Industry Looks For
Getting home insurance can be daunting, especially if you have an older property. By knowing what the insurance industry looks for, though, you can address the red flags and up your chances of getting better coverage at lower prices.
Keep reading our site to see more informative articles.








Business
Trader Vic’s Returns to Its Oakland Roots
Trader Vic’s, the internationally recognized brand and birthplace of the original Mai Tai, has officially returned to its roots in Oakland. Originally founded in 1934 on San Pablo Avenue before moving to Emeryville, the hospitality giant has launched Trader Vic’s Outpost at Oakland International Airport’s Terminal 2. The new full-service location offers travelers breakfast, lunch, dinner, and cocktails in a 108-seat space designed to celebrate the city’s status as a top national food destination. Visit the website to read more.
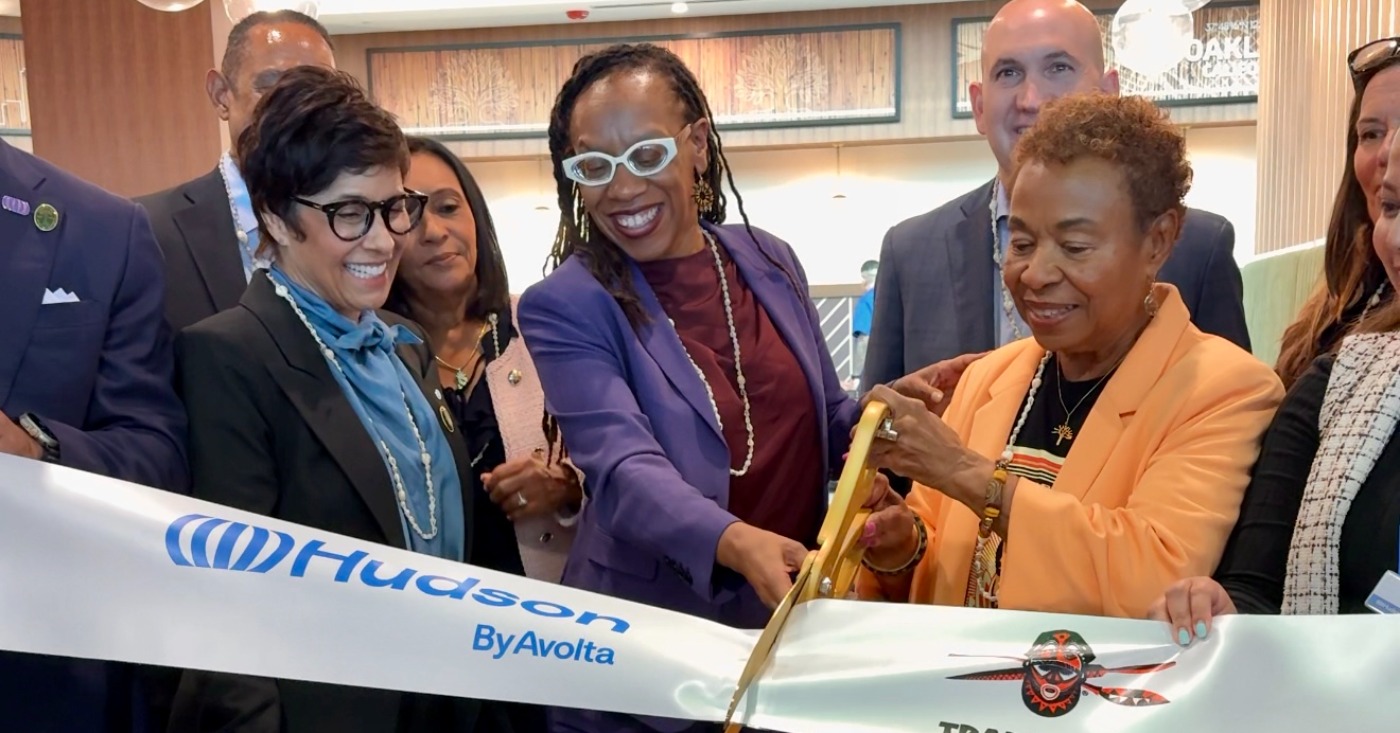
Oakland has always been a city of innovators, entrepreneurs, visionaries, and world-class hospitality. Trader Vic’s—the birthplace of the original Mai Tai – first opened in Oakland back in 1934 on San Pablo Avenue, long before becoming an internationally recognized global brand.
More than 50 years after it moved to Emeryville, Trader Vic’s is returning to its roots. Oakland Mayor Barbara Lee touts the return as another victory for Oakland.
“My administration is deeply committed to backing businesses like Trader Vic’s and Plum Market—partners who invest in our city, uplift our local workforce, and support thousands of local jobs,” Lee said.
The latest Trader Vic’s – called Trader Vic’s Outpost – is located at the Oakland International Airport in Terminal 2 near Gate 25 and had a soft opening in August.
With 108 dining seats, 28 bar seats and a counter for standing-room customers, travelers from around the world can have a full-service restaurant and bar experience or take-out for those with planes to catch.
Open from 6 a.m. to 10 p.m., breakfast, lunch, dinner, cocktails will be served.
Trader Vic’s returning to its roots confirms Condé Nast’s decision to name Oakland the #1 Food City in America two years in a row, and just earlier this month, ranked Oakland #6 on their list of Best Cities in the U.S.!
“The opening at OAK is incredibly meaningful for us,” said Rhett Rosen, CEO of Trader Vic’s Hospitality Group, according to the company website. “Trader Vic’s was born in the Bay Area, and this new location gives us the chance to welcome travelers with a taste of that original spirit before they take off. It brings together everything people love about Trader Vic’s — great cocktails, flavorful food, warm hospitality and a little sense of escape — in a place that connects Oakland to the world.”
Trader Vic’s is an Oakland institution and one of the region’s most recognizable hospitality brands, said Port of Oakland Director of Aviation Craig Simon on the web site.
“Travelers are increasingly seeking dining options that are memorable, locally rooted, and uniquely representative of the communities they are visiting. Trader Vic’s delivers all of that while providing a high-quality food and beverage experience for our guests. We are proud to welcome this hometown favorite to Terminal 2,”
The original Trader Vic’s in Oakland:
In 1934, with an investment of $500, Bergeron opened his initially small restaurant at 65th Avenue and San Pablo, serving comfort foods for lunch and dinner and beers and whiskeys. As his clientele grew, so did his restaurant, expanding space and menu options. After visiting this establishment, famed San Francisco Chronicle columnist Herb Caen proclaimed that the “best restaurant in San Francisco is in Oakland.”
There were as many as 25 franchises worldwide, including the U.S. Trader Vic’s is now headquartered in Martinez.
Business
Oakland Coal Terminal Backed by Trump Would Be Bigger, Dirtier Than Promised, Says Report
A recent feasibility study commissioned by potential investors says an Oakland coal terminal backed by President Donald Trump could export 13 million tons a year — three times the amount estimated in an earlier environmental review. Surprisingly, the report also contradicts devel
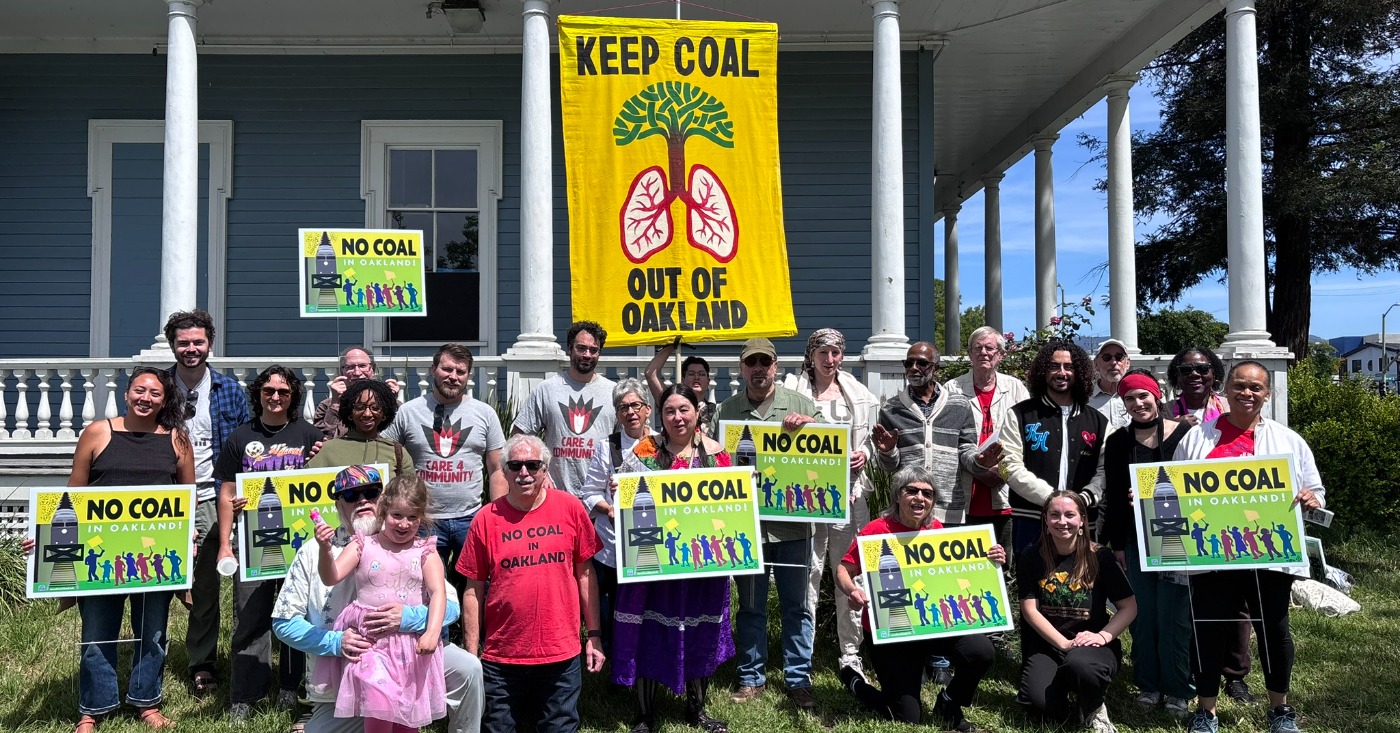
A recent feasibility study commissioned by potential investors says an Oakland coal terminal backed by President Donald Trump could export 13 million tons a year — three times the amount estimated in an earlier environmental review.
Surprisingly, the report also contradicts developers’ and project advocates’ repeated pledges that the coal would be stored in a covered terminal. Instead, the millions of tons of coal shipped annually from inland states to the West Gateway terminal in Oakland would be stored in “two open-air bunkers,” with about 150,000 tons of coal per stockpile, before being sent overseas, according to the recent report cited by the L.A. Times. (https://ruic.utah.gov/wp-content/uploads/2026/09/Port-Study-RUIC-Bulk-Commodity-Ocean-Terminals-Study.pdf)
Residents and clean air advocates have long expressed concerns that coal dust would worsen pollution in West Oakland and throughout the East Bay.
The proposed site of the Oakland Bulk and Oversized Terminal (OBOT) is located at the former Army base near the Port of Oakland, which developer Phil Tagami has been trying for years to turn into a shipping terminal despite determined community opposition.
Trump announced a $75-million investment in the project in June, about a third of its estimated cost. The new terminal would be the largest coal export site on the West Coast, transporting coal to Japan, South Korea, Taiwan, Vietnam and Malaysia, according to the Trump administration.
Opponents say a new terminal would undermine years of progress cleaning up the air in West Oakland, which has a history of disproportionate pollution and high asthma rates due to its proximity to the port and other industry.
According to No Coal in Oakland organizer Ted Franklin, who has been active for 11 years in the fight to stop the coal terminal, the report indicates that investors may be looking for a cheaper way to build the terminal.
“We were shocked but not surprised” by the report, Franklin said. “Basically, it seems that the plan now is to store open piles of coal, which is a less expensive project than creating a completely enclosed facility.”
The threats that the project poses are real, but it faces a lot of economic and legal hurdles, he said.
Coal production is in permanent decline worldwide, he said, wondering who was going to “invest money in an industry that has no future.”
Further, the project has not yet attracted big investors. “There’s no bank, no financing, no financial institution backing this,” he continued.
A major legal hurdle facing the project is the passage of Assemblymember Mia Bonta’s bill, AB 40, the Community-First Coal Review Act, signed into law by Gov. Gavin Newsom on Sept. 30.
The law requires developers of large-volume bulk coal facilities to complete a full Environmental Impact Report (EIR) under the California Environmental Quality Act (CEQA) before they can operate.
The law was specifically designed to block or delay the coal terminal project.
The report to potential developers was produced by consulting groups Norda Stelo and Wood Mackenzie in July and released this month. It was commissioned by the Rural Utah Infrastructure Coalition, made up of eight Utah counties that are considering investing about $43 million into the terminal to receive Utah coal.
The consultants produced their findings after visiting Oakland, examining engineering documents and holding discussions with Savage Cos., a Utah-based transport and logistics company selected to operate the facility
Research has shown that coal terminal operations can be dangerous to public health. The ports of Los Angeles and Long Beach moved away from open-air coal and petroleum coke storage three decades ago.
The report says that the site could process 12 million metric tons, or 13.2 million tons, of coal each year, three times more than the terminal’s approved environmental impact report from 2002 and its 2012 addendum. Neither document mentions coal specifically, but rather bulk commodities.
The coal arriving in Oakland could also be dirtier then had been previously stated, according to the report. Project officials previously said the terminal would handle only high-grade western bituminous coal from Utah, but the recent report says it will also handle Powder River Basin coal from Wyoming and Montana, known to be much dustier.
Nor does the report mention plans to cover the rail cars to prevent pollution, though project officials previously promised they would only utilize coal transported in covered rail cars.
“It appears the developers want to build something much bigger and more polluting than anything they previously revealed, either in court or to the West Oakland community,” said Colin O’Brien, deputy managing attorney at the nonprofit Earthjustice, speaking to the L.A. Times.
The report indicates that the project may be much more expensive and take longer to complete than anticipated. The Energy Department estimates the terminal will cost about $231 million, but the report places the price at between $430 million and $625 million.
The terminal will take 53 months to complete according to the report, significantly longer than Trump’s promise of exports beginning in 2028.
Ted Franklin’s column, “Utah Study Blesses Investment in Oakland Coal Terminal but Leaves Key Questions Unanswered” is available at https://nocoalinoakland.info/utah-study-blesses-investment-in-oakland/

To enlarge your view of this issue, use the slider, magnifying glass icon or full page icon in the lower right corner of the browser window.


Mayor Barbara Lee Holds Special State of the City Address in Deep East Oakland

Practitioners of African Traditional Spirituality Offer Ancestral Reverence Ritual Oct. 31

It’s Time to Lose Weight Before the Holidays

Trader Vic’s Returns to Its Oakland Roots

Oakland Coal Terminal Backed by Trump Would Be Bigger, Dirtier Than Promised, Says Report

Opponents Smear Effective African American Transit Director as Election Nears

Oakland Post: Week of October 14 – 20, 2026

OP-ED: The Black Church Writes AI’s Next Chapter

OP-ED: The Black Church Writes AI’s Next Chapter

WCCUSD Joins Statewide Organic School Food Purchasing Cooperative

Democrats, Community Groups Back Measure EE to Change How Oakland Is Governed

Four Tips to Help You Plan a Holiday “Staycation”

Veterans Housing Project Proposed for South Richmond
PRESS ROOM: Transformative Justice Coalition 2026 Voting Rights Champion Awards Reception ‘Yesterday Is Today: The Battle For Voting Rights

Mayor Lee Delivers 2026 State of the City Address: ‘Oakland Continues to Be on the Move’

Misnamed ‘Parent’ PAC Seeks to Influence Oakland School Board Elections

Oakland Post: Week of September 2 – 8, 2026

Oakland Post: Week of September 9 – 15, 2026

Poll: Becerra Widens His Lead Over Hilton; Californians Split on Wealth Tax

County Office of Education Says OUSD Finances Are Getting Healthier, Materially Stronger

Richmond Tiny House Village Farm & Garden Set to Open Gates on Sept. 26

Latest Massacre in Haiti Reveals Cruelty U.S. Deportations

Mayor Lee Announces $1 Million Kaiser Permanente Grant for Pilot Program to Address Homelessness, Clean Up Public Spaces throughout Oakland

OPINION: Nolan Wells’ Death One of Several Signifying Racial Terror Lives on in U.S. South

BLACspace Cooperative Invites Bay Area to Experience Oakland’s Black Cultural Ecosystem Through a BLAC Map Tour + Party

Zakiya Jendayi Arrested, Locked Out of Home by Sheriff’s Deputies

Democratic Clubs Interview Candidates for Oakland School Board

Listening as a Lifeline: A Doula’s Witness to Black Maternal Health

Oakland Post: Week of September 16 – 22, 2026

Oakland People’s Arms Embargo Coalition Demands End to Military Shipments Thru Oakland

The Conversation With Al McFarlane 6/23/26

Media Monday 6/22/26

LIVE! ASK ALMA! — TUES. 6.23.26 7PM EST

Car Buying Secrets: 4 Hidden Checks Before You Sign!

Is This 550 HP Charger Worth YOUR Money? AutoNetwork Review

Celebrating Juneteenth – Frederick Douglass on education and resistance

LIVE! — ASK ALMA! — TUES. 6.19.26 7PM EST

Hyundai Ioniq 5 Parking, Safety, and 360 View #shorts

2025 Ioniq 5 New Wiper & Powerful Performance! #shorts

Electric SUV Range: Is 259 Miles Enough? #shorts

EV Charging: How Fast Can You Charge an Electric Vehicle? #shorts

Biometric Cooling… Messaging Seats…Come on! 2025 Infiniti QX80 Autograph 4WD

Charged Up: Witness the Magic of a Fully Electric Car! #shorts

Range Rover Sport PHEV Included…: See What’s Inside This Luxury SUV! #shorts

Invisible Hood View: Perfect Parking with X-Ray Vision! #shorts
-
 Economy3 weeks ago
Poll: Becerra Widens His Lead Over Hilton; Californians Split on Wealth Tax
-
 Business3 weeks ago
County Office of Education Says OUSD Finances Are Getting Healthier, Materially Stronger
-
 Business4 weeks ago
Mayor Lee Announces $1 Million Kaiser Permanente Grant for Pilot Program to Address Homelessness, Clean Up Public Spaces throughout Oakland
-
 Art3 weeks ago
BLACspace Cooperative Invites Bay Area to Experience Oakland’s Black Cultural Ecosystem Through a BLAC Map Tour + Party
-
 Lead Story2 weeks ago
Zakiya Jendayi Arrested, Locked Out of Home by Sheriff’s Deputies
-
 Black History2 weeks ago
Listening as a Lifeline: A Doula’s Witness to Black Maternal Health
-
 Activism4 weeks ago
Oakland Post: Week of September 16 – 22, 2026
-
 Uncategorized4 weeks ago
Oakland People’s Arms Embargo Coalition Demands End to Military Shipments Thru Oakland
